

Since March 2026, Motorola Solutions has been in a holding pattern, floating around $456.35. The stock also fell short of the S&P 500’s 18% gain during that period.
Given the weaker price action, is now a good time to buy MSI? Or should investors expect a bumpy road ahead? Find out in our full research report, it’s free.
Why Is Motorola Solutions a Good Business?
Born from the company that invented the first portable handheld police radio in 1940, Motorola Solutions (NYSE:MSI) provides mission-critical communications, video security, and command center software solutions for public safety agencies and enterprise customers.
1. Skyrocketing Revenue Shows Strong Momentum
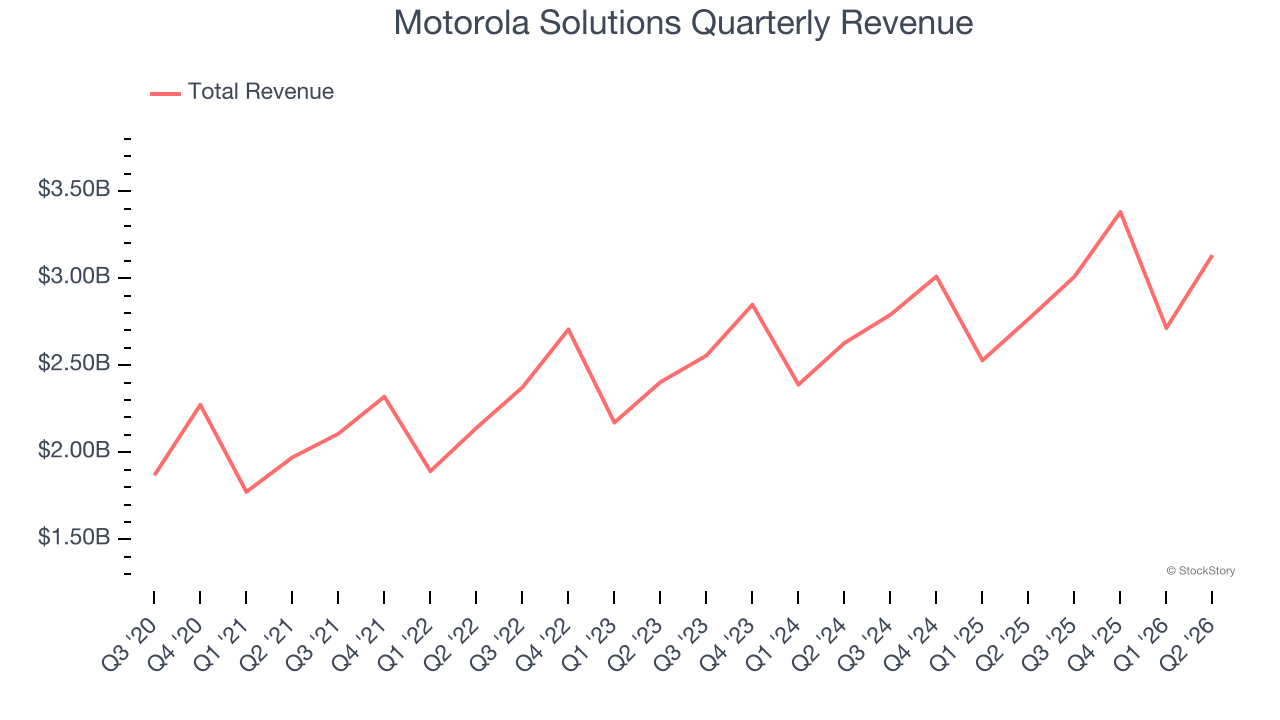
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Motorola Solutions grew its sales at an impressive 9.2% compounded annual growth rate. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Adjusted Operating Margin Rising, Profits Up
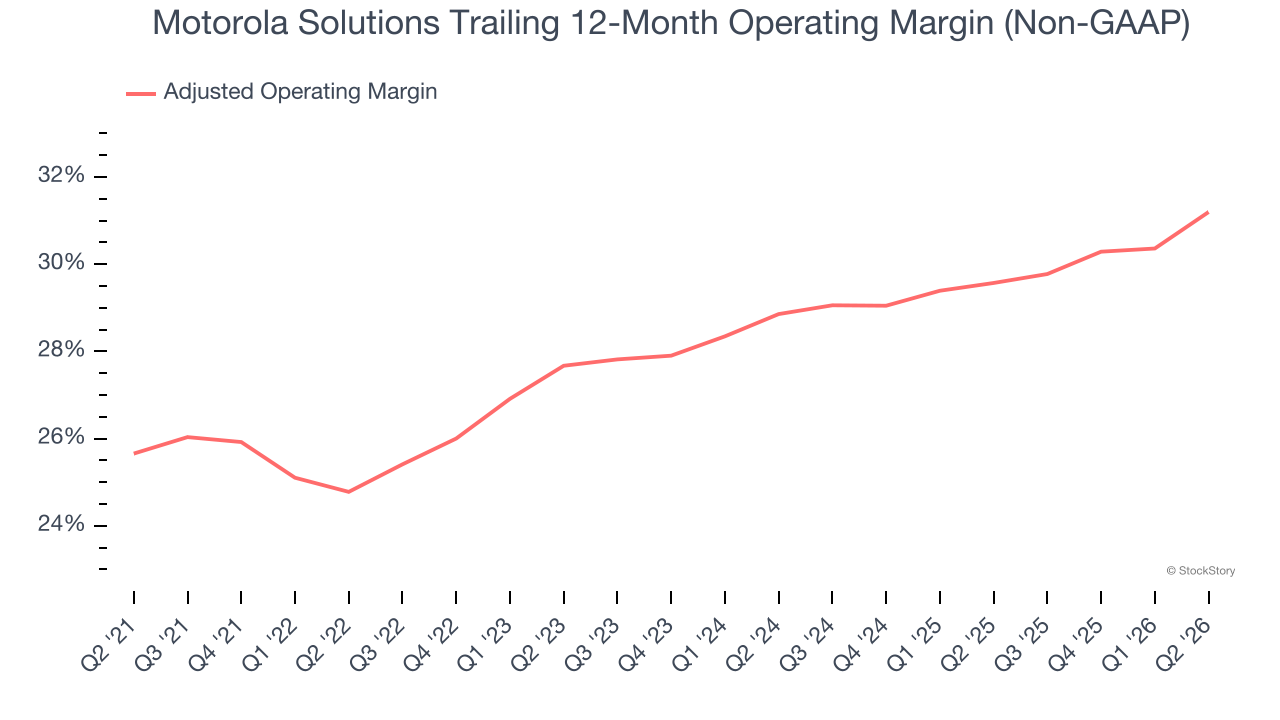
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Looking at the trend in its profitability, Motorola Solutions’s adjusted operating margin rose by 6.4 percentage points over the last five years, as its sales growth gave it immense operating leverage. Its adjusted operating margin for the trailing 12 months was 31.2%.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
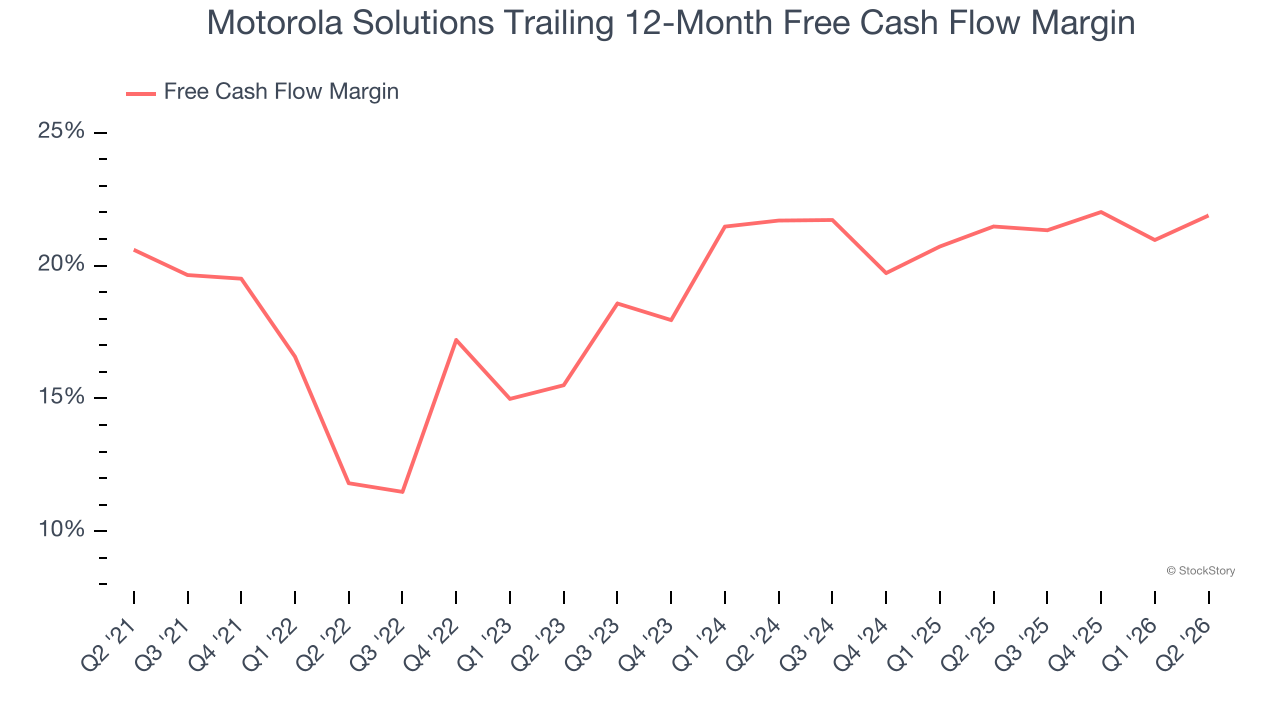
Motorola Solutions has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the business services sector, averaging 18.9% over the last five years.
Final Judgment
These are just a few reasons why Motorola Solutions ranks highly on our list. With its shares lagging the market recently, the stock trades at 25.4× forward P/E (or $456.35 per share). Is now the time to initiate a position? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.