
Sysco currently trades at $78.11 per share and has shown little upside over the past six months, posting a small loss of 4.3%. The stock also fell short of the S&P 500’s 16.2% gain during that period.
Is there a buying opportunity in Sysco, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Sysco Will Underperform?
We’re sitting this one out for now. Here are three reasons we avoid SYY, plus one stock we’d rather own.
1. Sales Volumes Stall, Demand Waning
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Consumer Discretionary - Distributors company because there’s a ceiling to what customers will pay.
Over the last two years, Sysco failed to grow its units sold. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Sysco might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 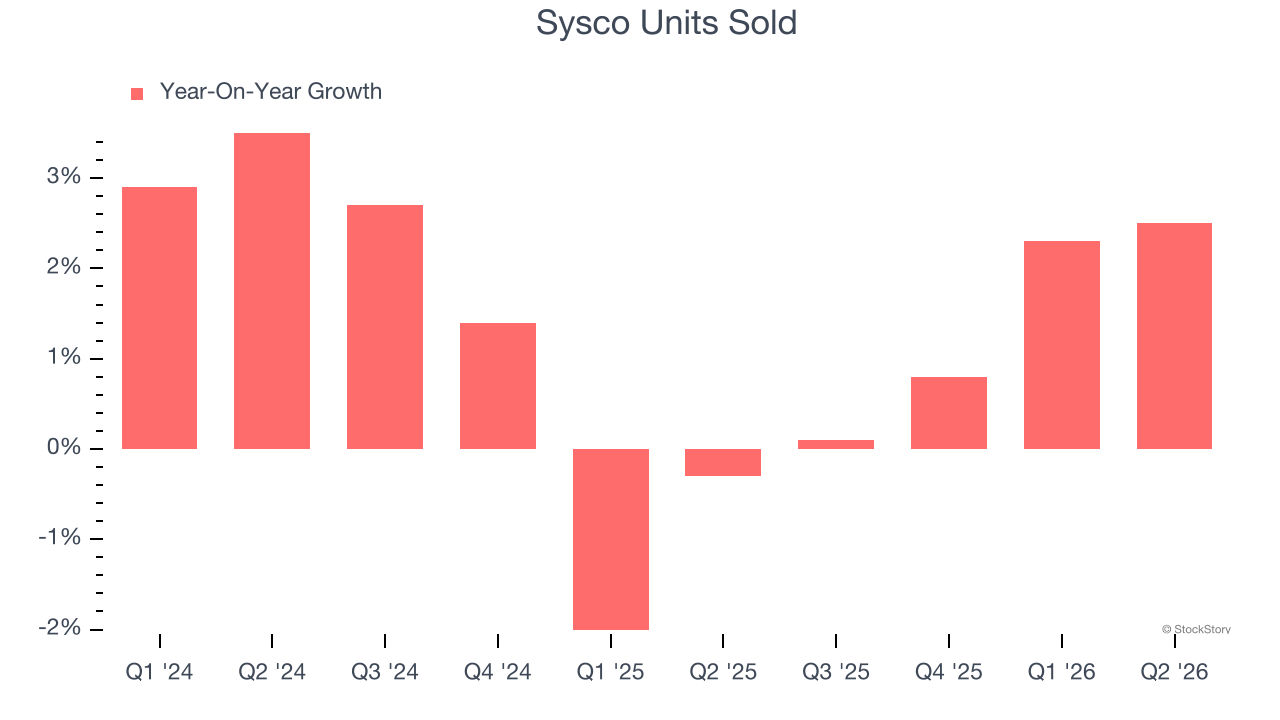
2. Free Cash Flow Projections Disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates show they’re expecting Sysco’s free cash flow margin of 2.3% for the last 12 months to remain the same.
3. New Investments Fail to Bear Fruit as ROIC Declines
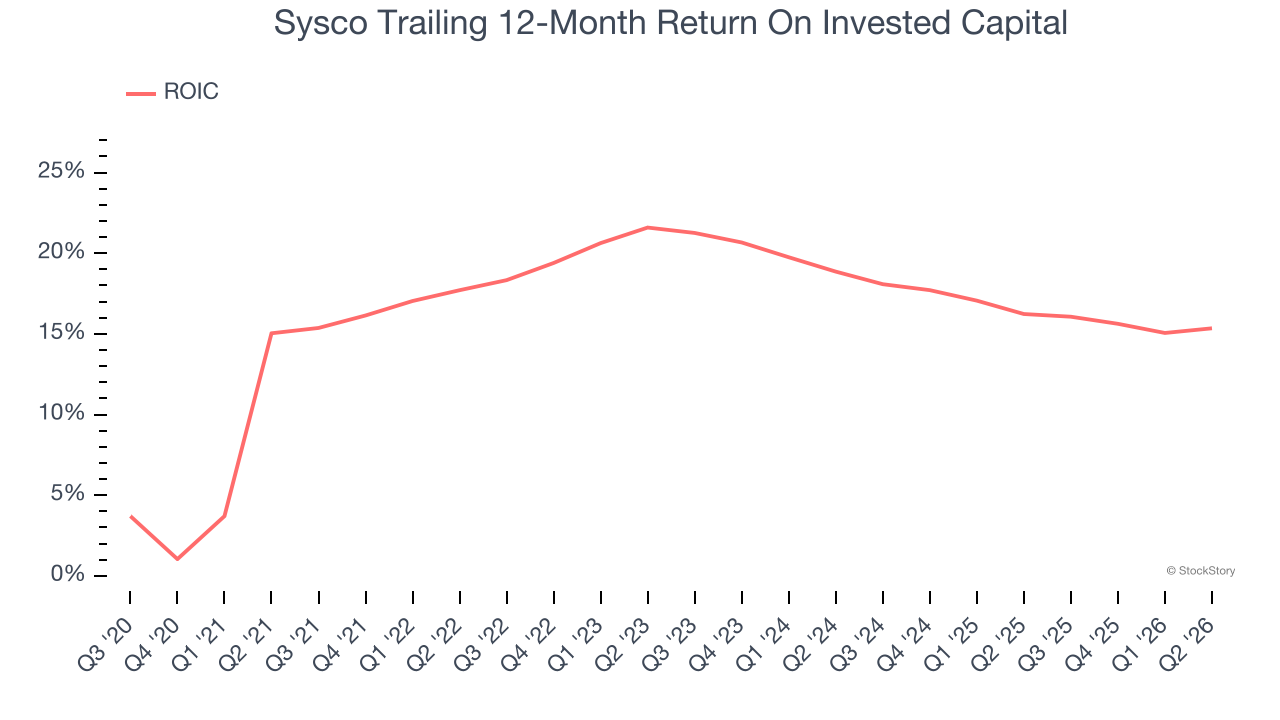
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Sysco’s ROIC averaged 3.9 percentage point decreases each year. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
Sysco falls short of our quality standards. With its shares trailing the market in recent months, the stock trades at 15.6× forward P/E (or $78.11 per share). This valuation tells us a lot of optimism is priced in - you can find more timely opportunities elsewhere. We’d suggest looking at the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.